Top 5 UK housing developments driving the 2026 recovery
After several difficult years for residential development, signs of renewed momentum are emerging across UK housing. Higher borrowing costs, construction inflation, planning delays and viability pressures have challenged developers, contractors and investors, but activity supported by public investment and major regeneration programmes is creating a more positive outlook in 2026.
Homes England figures provide some of the clearest evidence. Programmes managed by the agency delivered 42,433 housing starts during 2025/26, an increase of 11 per cent year on year, alongside 40,332 completions, up 9 per cent. Affordable housing accounted for 32,243 of those completions, representing 80 per cent of the total. Social rent completions reached 9,381, a 65 per cent increase.
Those figures do not mean every part of the market has recovered. Instead, they point towards a changing model for UK construction, with public investment, affordable housing, institutional capital and brownfield regeneration becoming increasingly important.
From major London schemes to regional city regeneration, these five housing developments illustrate where that momentum is translating into physical construction.
1. Silvertown, London: 7,000 homes and a new development model
Few projects demonstrate the changing relationship between the public and private sectors as clearly as Silvertown in London’s Royal Docks.
The regeneration project is planned to deliver 7,000 homes as part of the transformation of a major east London site. In June 2026, the Mayor of London announced a £100 million investment to join the Silvertown Partnership through the new City Hall Developer initiative. City Hall described the commitment as one of the largest investments made by a London mayor in a single development site.
The significance for the UK housing sector extends beyond the headline number of homes. City Hall is taking a more active role in development, with its approach explicitly influenced by Singapore’s state-led housing model.
For contractors and the wider supply chain, large regeneration projects such as Silvertown offer substantial long-term opportunities. Residential construction is accompanied by the infrastructure, public realm, commercial space and services required to turn former industrial land into functioning neighbourhoods.
Silvertown also demonstrates how government capital can help reduce barriers surrounding strategically important projects. In a market where viability has become one of the biggest obstacles to construction, greater public-sector involvement could become a defining characteristic of the recovery.
The project’s scale makes it an important indicator of whether London can translate ambitious housing targets into sustained construction activity.
2. Bollo Lane, London: Setting a Passivhaus benchmark
Bollo Lane in Ealing combines three of the biggest themes influencing residential construction in 2026: affordability, brownfield development and building performance.
Construction officially began in March 2026 on the 900-home development beside Acton Town station. Half of the homes, 450 properties, will be affordable. The project is being delivered by the West London Partnership, a joint venture between Places for London and Barratt London.
The development will proceed across two phases. The first, in partnership with Grainger, will provide private and intermediate rental homes. The second, involving Metropolitan Thames Valley Housing, will include social rent, intermediate and private housing. Completion is scheduled for December 2029.
What makes Bollo Lane particularly noteworthy for the construction industry is its environmental ambition. Barratt Redrow describes it as Europe’s largest Passivhaus scheme.
Passivhaus standards place significant emphasis on insulation, airtightness, ventilation and energy efficiency. Delivering these requirements across a development approaching 1,000 homes takes the conversation about low-energy construction beyond individual demonstration projects and into large-scale residential delivery.
For the UK construction industry, this creates opportunities but also technical demands. Contractors and suppliers increasingly need expertise in high-performance building envelopes, mechanical ventilation, quality control and energy-efficient systems.
Bollo Lane therefore represents more than another London housing scheme. It provides a glimpse of how sustainability standards could influence the technical specification of future UK housing developments.
3. Canalside South, Wolverhampton: Brownfield regeneration becomes housing
Wolverhampton’s Canalside South provides perhaps the clearest evidence in this list of construction activity turning into completed homes.
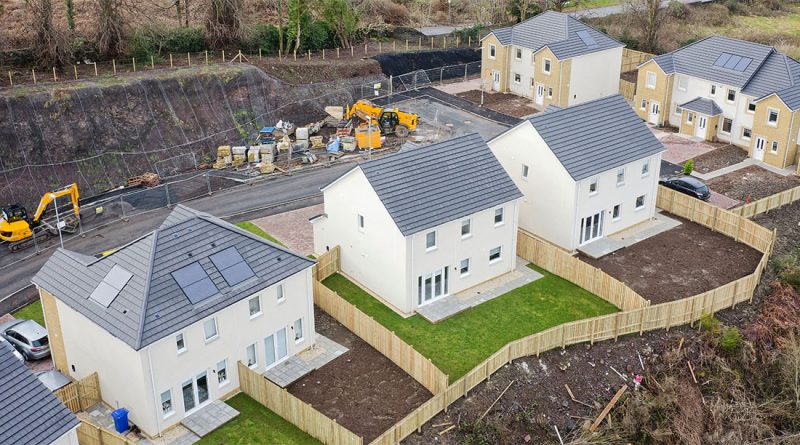
The £150 million development is transforming a former British Steel site and Crane Foundry that had been derelict for around 15 years. Construction began in early 2025, and by August 2026 the first 30 family homes were ready for residents. More than £25 million had already been invested in land assembly, remediation, enabling works, groundworks and construction.
The development will ultimately provide 533 energy-efficient houses and apartments by 2030. Plans include 378 townhouses, 145 one and two-bedroom apartments and 60 co-living apartments, as well as seven acres of green space and commercial accommodation created within disused railway arches.
Importantly for the civil engineering sector, this is not simply a housebuilding project. Bringing a former industrial site back into productive use has required remediation, infrastructure and substantial enabling works before residential construction could advance.
The development also provides an example of institutional investment supporting regional housing. Kennedy Wilson has purchased 131 plots for rental homes, while half of the scheme’s 378 family houses had already been sold off-plan by August.
Canalside South is part of a wider Wolverhampton Canalside vision for approximately 1,000 homes. Its progress demonstrates how difficult brownfield sites can become valuable housing assets when local authorities, developers and investors align behind regeneration.
4. Grey Mare Lane, Manchester: Social housing returns to the pipeline
The recovery in UK housing cannot be measured exclusively through private sales. Social and affordable housing will also be critical to maintaining construction pipelines, particularly when private demand is constrained.
That makes Grey Mare Lane in Beswick, Manchester, an important development to watch.
In January 2026, Great Places Housing Group marked the start of construction at Coalbrook Court, a £21 million affordable housing development being delivered with Caddick Construction. It will provide 82 one and two-bedroom apartments, all for social rent.
The project forms part of a much larger regeneration programme for Grey Mare Lane, where the wider masterplan envisages around 1,000 new homes.
For construction businesses, projects of this type provide a potentially important counterweight to volatility in private housebuilding. Housing associations, local authorities and government-backed programmes can sustain projects based on long-term housing need rather than relying entirely on private sales rates.
The latest Homes England figures reinforce that shift. Of 40,332 homes completed through its programmes in 2025/26, 32,243 were affordable. Social rent completions alone increased by 65 per cent compared with the previous year.
Grey Mare Lane therefore represents a wider structural change. Affordable and social housing are becoming increasingly important sources of workload for contractors and consultants as Britain seeks to increase housing supply.
5. Anglia Square, Norwich: Unlocking complex urban sites
Anglia Square demonstrates another major challenge facing the sector: how to unlock housing on complicated urban brownfield land.
The £350 million Norwich regeneration project is planned to deliver around 1,100 homes on an 11-acre former shopping centre site. At least 50 per cent of homes in the first two phases are expected to be affordable. The scheme is being advanced through an investment partnership between Norwich City Council and Aviva Capital Partners, with support from Homes England.
By February 2026, demolition had reached another significant milestone with work beginning on the site’s multi-storey car park.
Homes England funding has played a crucial role in unlocking the site. Norwich City Council says a £34 million grant helped enable its acquisition and redevelopment, while the wider project could create more than 3,500 jobs.
Anglia Square highlights why housing delivery cannot be considered separately from civil engineering and regeneration. Before thousands of people can move into new homes, existing structures may need demolition, contaminated land can require remediation, utilities need upgrading and public spaces must be created.
That work represents a significant opportunity for the construction supply chain, particularly as policymakers increasingly look towards brownfield land to increase housing supply while limiting pressure on undeveloped sites.
A different kind of UK housing recovery
These five projects suggest that the 2026 recovery is not simply a return to the housebuilding market that existed before interest rates and construction costs rose.
Silvertown demonstrates stronger public-sector participation. Bollo Lane combines affordable housing with ambitious building-performance standards. Canalside South shows brownfield regeneration translating into occupied homes. Grey Mare Lane illustrates the growing importance of social housing, while Anglia Square highlights the investment and enabling work required to unlock complex urban sites.
The common denominator is collaboration.
Developers, local authorities, housing associations, institutional investors, Homes England and contractors are increasingly combining capital and expertise to move projects forwards.
There are still significant challenges for UK construction, and the latest statistics should not be mistaken for a complete market recovery. Yet the direction of travel is encouraging. Homes England-supported starts increased 11 per cent in 2025/26 and completions rose 9 per cent, providing tangible evidence of greater activity.
For contractors, civil engineers and suppliers, the opportunity extends beyond building houses. The next generation of UK housing developments will require remediation, infrastructure, low-energy construction, transport connections and high-quality public realm.
If 2026 proves to be the beginning of a sustained housing recovery, these five developments offer an early picture of what that recovery could look like: more collaborative, more regeneration-led and increasingly dependent on construction expertise that extends far beyond the front door.