Why London remains the world’s second-costliest city to build in
Subscribe to our free newsletter today to keep up to date with the latest construction and civil engineering news.
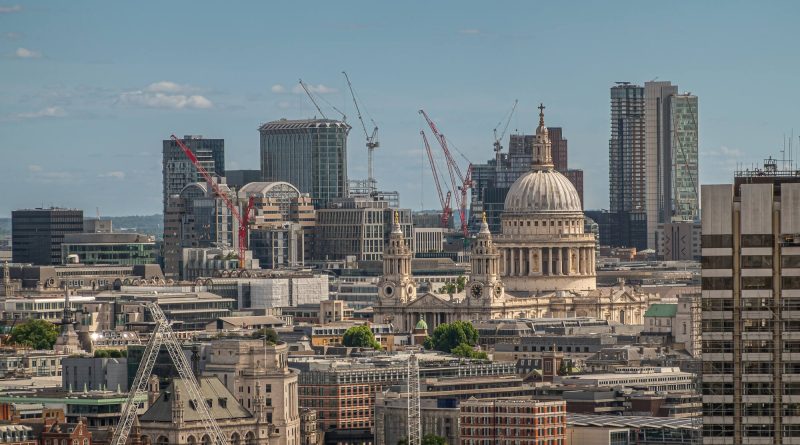
London has retained its position as the world’s second most expensive city for construction, behind Geneva and ahead of Zurich, according to Arcadis’ 2026 International Construction Cost Index.
The ranking places London above Munich, Copenhagen, New York City and San Francisco in a comparison of 100 major cities. Yet the significance of London’s position extends beyond the familiar story of high labor, material and land costs.
Arcadis argues that construction markets are moving away from a period dominated by inflation and into a more selective investment cycle. Capital is still available, but clients are applying tighter tests to viability, schedules and delivery risk. In that setting, the ability to build with confidence may matter more than securing the lowest headline price.
For London, this is a critical distinction. The city’s construction premium reflects not only how much projects cost, but how difficult they are to design, approve, procure and deliver.
London’s high costs reflect the complexity of its market
London’s place near the top of global cost rankings is not a temporary anomaly. It is the product of a mature market where several sources of cost pressure operate at once.
The city has demanding planning and regulatory requirements, limited sites, congested logistics networks and strong competition for specialist labor. Many projects are delivered in dense urban locations where access, noise, safety and sequencing constraints add time and expense.
London also has a large concentration of technically complex developments. Commercial offices, laboratories, hospitals, data centers, major residential schemes and mixed-use projects often require sophisticated building systems and high environmental performance. These assets can be expensive to design and construct even before market-wide pressures are taken into account.
Arcadis reports that investment is increasingly directed toward high-performing buildings that support long-term economic activity, including health care facilities, advanced manufacturing sites, laboratories, modern workplaces and digital infrastructure. Such projects tend to rely on specialist contractors, imported equipment and supply chains with limited spare capacity.
The result is a market where high costs can be a sign of depth and demand, but also a warning about execution risk.
London remains attractive because it offers access to capital, talent, tenants and global businesses. That does not mean every proposed scheme is viable. Higher financing costs, volatile energy markets, trade uncertainty and supply chain constraints are increasing pressure on project economics. Arcadis notes that these conditions are raising the value of early cost intelligence, scenario planning and procurement discipline.
Developers can no longer rely on future market growth to absorb weak assumptions made during design. A project that begins with an unrealistic budget or schedule may struggle to recover once specialist packages are procured and construction is underway.
Delivery certainty is replacing lowest price as the central objective
For years, construction procurement often treated cost reduction as the primary measure of success. In London’s current market, that approach can create false confidence.
A lower tender may depend on optimistic assumptions about labor availability, design completion, material lead times or risk transfer. When those assumptions fail, the eventual cost can exceed the price of a more realistic bid.
The more useful question is not whether a project can secure a low initial price. It is whether the client, contractor and supply chain can deliver the required building within an acceptable range of cost and time.
Arcadis’ 2026 report frames cost, capacity, delivery risk and investor confidence as connected factors. It states that lower construction prices do not automatically produce more reliable outcomes. Grid access, permitting, skills, infrastructure and specialist contractor availability can determine whether a project reaches construction at all.
London offers a clear example of this shift.
Clients seeking greater control will need to make key decisions earlier. Contractor input during design can identify buildability problems before they become expensive. Early procurement of long-lead equipment can protect schedules. Transparent risk allocation can reduce the defensive pricing that appears when contractors are asked to accept risks they cannot manage.
This does not remove competitive tension from procurement. It changes what clients should ask the market to compete on.
Price remains important, but it should sit beside program credibility, supply chain access, design management and evidence of delivery capability. The lowest bid has little strategic value when it is based on assumptions that cannot survive the construction phase.
For contractors, the same principle applies. Firms that can provide reliable forecasts, identify risks early and communicate the consequences of design decisions may become more valuable than those that compete mainly through price.
London projects need stronger decisions before construction begins
London’s ranking has direct consequences for developers, investors and occupiers.
Project viability must be tested against a wider range of scenarios. A single cost plan based on favorable assumptions is no longer enough. Clients need to understand how financing changes, procurement delays, design revisions and supply shortages could affect the business case.
This is particularly relevant for developments that depend on fixed completion dates or early revenue generation. Data centers, hotels, offices and build-to-rent schemes can suffer material losses when delays prevent occupancy or postpone income.
Arcadis identifies speed to revenue and efficient capital deployment as central client concerns. It also argues that cost, schedule, procurement and risk decisions should be considered together before changes become difficult and expensive.
That places greater responsibility on the earliest stages of project development.
Clients may need to spend more on design coordination, market testing and preconstruction advice before approving a final investment decision. That can appear to increase early costs, but it may reduce exposure to larger problems later.
Value engineering will also need to become more disciplined. Cutting specifications without understanding operational consequences can reduce capital expenditure while weakening energy performance, maintenance efficiency or tenant appeal. A better approach is to assess whole-life value alongside the initial construction budget.
London’s second-place ranking should not be read simply as evidence that the city is becoming too expensive to build in. It shows that construction in the capital requires a level of planning and control that many project models were not designed to provide.
The city is likely to remain a high-cost market because it continues to attract complex investment and maintain demanding performance standards. The strategic challenge is to make those costs predictable.
For clients, the most successful projects will not necessarily be those with the lowest starting price. They will be the projects that enter construction with credible budgets, secured capacity, coordinated designs and a clear understanding of where risk sits.
In one of the world’s most expensive construction markets, certainty is no longer an administrative benefit. It is part of the investment case.
Source